
Derrick Kapitan
The Mortgage Coach
Contact Info:
About
Explore Our Services
Preview Our Rates
Access all your mortgage options with just one application. Preview today's rates first:
Blog
Mortgage Repayment Options in Canada - The Mortgage Coach
September 08, 2026
Explore mortgage repayment options, including payment frequency, amortization, accelerated payments and lump-sum payments, and how they can affect your mortgage.
Mortgage Repayment Plans & Options: How You Repay Your Mortgage Matters
When discussing a mortgage, one question tends to receive most of the attention:
“What’s the interest rate?”
The rate is important. But it is only one part of the overall cost of borrowing.
How you choose to repay your mortgage can also influence how quickly your principal balance declines, how much interest you pay over time, and how long you carry the mortgage.
Throughout this week's mortgage education series, we used one consistent example:
Mortgage: $500,000Illustrative interest rate: 4.45%Amortization: 25 yearsMonthly payment: approximately $2,753
We then changed different elements of the repayment strategy to demonstrate an important principle:
The mortgage may be the same, but different repayment choices can produce different outcomes.
Understanding Your Mortgage Payment
A traditional blended mortgage payment consists of two components:
Principal + Interest
The principal is the amount you borrowed and still owe. Interest is the cost charged for borrowing that money.
In the earlier years of an amortizing mortgage, a greater portion of each payment typically goes toward interest. As the outstanding principal declines, the allocation between principal and interest changes.
This is why reducing principal sooner can be important. A lower outstanding principal means there is less mortgage balance on which future interest is calculated.
Rather than only asking, “What is my monthly payment?”, it can be useful to also understand how that payment is reducing what you owe.
Regular Bi-Weekly vs. Accelerated Bi-Weekly
Payment frequency is another area where mortgage terminology can sometimes create confusion.
Using our $500,000 example, we compared:
Regular bi-weekly: approximately $1,271 × 26 payments per year
Accelerated bi-weekly: approximately $1,377 × 26 payments per year
Both involve making 26 payments each year, but the amount being paid is different.
With accelerated bi-weekly payments, approximately $2,753 more is paid toward the mortgage over the year—roughly equivalent to making one additional monthly payment.
The important lesson is that simply changing how frequently you make payments isn't necessarily what creates the larger potential savings.
It's the additional amount being applied toward the mortgage that helps principal decline faster.
Over time, that can potentially reduce interest costs and shorten the amortization.
25-Year vs. 30-Year Amortization
Amortization represents the length of time over which the mortgage is scheduled to be completely repaid.
A longer amortization can reduce the required monthly payment, which may provide additional cash-flow flexibility.
Using our illustrative $500,000 mortgage at 4.45%, we compared a 25-year and 30-year amortization.
The 25-year example had a monthly payment of approximately $2,753.
Extending the amortization to 30 years reduced the illustrative monthly payment to approximately $2,506, but extended repayment by another five years.
That illustrates the trade-off.
A longer amortization can mean:
Lower required payments today, but potentially more interest paid over time.
A shorter amortization generally means:
Higher required payments today, but faster principal repayment and potentially less total interest.
Neither option should automatically be considered better.
The appropriate structure depends on the borrower's financial circumstances, cash flow, goals and the mortgage products for which they qualify.
The question is not simply:
“How low can I make my payment?”
It is also:
“What does this repayment structure mean over the longer term?”
Increasing Your Regular Mortgage Payment
What happens if your financial situation improves after you obtain your mortgage?
Perhaps you receive a salary increase, finish paying off a vehicle, or simply have more room in your monthly budget.
Depending on your mortgage contract, you may be able to voluntarily increase your regular payment.
Using our illustrative example, increasing the approximately $2,753 monthly payment by 10% would bring it to approximately $3,029 per month.
That's roughly an additional $275 per month going toward the mortgage.
The additional amount can help reduce principal sooner, potentially shortening the amortization and reducing future interest costs.
However, there is an equally important consideration:
Cash flow.
The objective shouldn't simply be to pay as much as possible toward the mortgage.
A repayment strategy needs to comfortably fit your household budget and be sustainable alongside your other financial priorities.
Making a Lump-Sum Payment
Another repayment option may be making a lump-sum payment.
Perhaps you've received:
- a work bonus
- a tax refund
- an inheritance
- additional savings
Depending on the prepayment privileges contained in your mortgage contract, you may be able to apply some of that money directly against your outstanding principal.
In our example, we considered a $10,000 lump-sum payment on a $500,000 mortgage.
That's equivalent to 2% of the original mortgage amount.
A lump-sum payment can immediately reduce the principal balance. Because future interest is then calculated on a lower outstanding balance, the payment may also reduce future interest costs and shorten the remaining amortization.
Timing can matter as well.
Generally, reducing principal earlier provides more time for the potential interest-saving effect to accumulate.
Before making any additional payment, however, it's important to understand the prepayment privileges, limits and conditions contained in your mortgage contract.
The Bigger Mortgage Conversation
Over the course of the week, we started with the same mortgage:
$500,000. 4.45% illustrative interest rate. 25-year amortization.
What changed were the repayment decisions.
We looked at:
Principal and interest — understanding where your mortgage payment goes.
Payment frequency — understanding the difference between regular and accelerated payments.
Amortization — balancing monthly affordability against longer-term borrowing costs.
Payment increases — applying additional money toward principal when your budget permits.
Lump-sum payments — using available prepayment privileges to reduce principal.
Each decision can influence how your mortgage develops over time.
Your Mortgage Is More Than a Rate
Finding a competitive mortgage rate matters.
But mortgage planning shouldn't necessarily end once the rate and monthly payment have been determined.
Understanding the repayment features contained in the mortgage can be equally important.
When arranging, renewing or reviewing your mortgage, consider asking:
What repayment options are available to me?
Can I increase my regular payment?
What are my lump-sum prepayment privileges?
Would an accelerated payment schedule fit my budget?
How does my amortization affect both today's payment and my longer-term cost?
There isn't one repayment strategy that is right for everyone.
The objective is to understand your choices and select a structure that works with your financial circumstances today while supporting where you want to be in the future.
The rate matters. Your repayment strategy matters too.
The Property Journey
Getting In • Growing • Staying
A mortgage is not simply about obtaining financing. It's about understanding how that financing fits into the broader property journey—from purchasing a home, to building equity, to managing the mortgage over the years ahead.
Know your mortgage. Understand your options. Make informed decisions.
Disclaimer: The $500,000 mortgage amount, 4.45% interest rate, payments and calculations used in this article are hypothetical and for illustrative and educational purposes only. Actual mortgage rates, payments, interest costs, savings and repayment options will vary by borrower, lender, mortgage product and terms. This information is not intended as financial advice.
Ready to start your Property Journey? Connect with me today to get started.
Derrick Kapitan Mortgage Agent Level 1 | Lic. M24003293 The Mortgage Coach | FSRA #13120
Sharing Knowledge. Sharing Life Experience. Continuous Learning.
📞 647-219-4743 📧 derrickkapitan@themortgagecoach.ca 🌐 www.themortgagecoach.ca
Week 35 August 30 2026
Mortgage Refinance & Debt Consolidation: Does It Make Sense?
September 08, 2026
Can refinancing help consolidate debt and improve cash flow? Learn what to consider before using your home equity and when refinancing may not be the right solution.
Refinance & Debt Consolidation: When Does a Refinance Actually Help?
For homeowners carrying credit-card balances, lines of credit or other higher-interest debt, refinancing can seem like an attractive solution.
And in the right circumstances, it can be.
Using available home equity to consolidate debt may reduce interest costs, simplify several payments into one and improve monthly cash flow. That breathing room can make a meaningful difference to a household budget.
But there is an important question to consider before focusing on the new mortgage payment:
Will refinancing actually leave you in a better financial position?
A refinance should be more than a way of moving debt from one place to another. It should be part of a longer-term financial strategy.
A Lower Payment Isn't the Whole Story
Imagine having several credit cards, a line of credit and perhaps another loan.
Consolidating those obligations into a mortgage could significantly reduce the amount required each month. But a lower monthly payment does not necessarily mean a lower total cost.
When short-term consumer debt is transferred into a mortgage and repaid over a much longer period, the repayment timeline matters.
That is why a debt-consolidation strategy should consider both monthly affordability and the longer-term cost of borrowing.
The objective isn't simply a smaller payment. It is a stronger financial position.
Before Consolidating Debt, Understand What Created It
One of the most important questions in a debt-consolidation conversation may have very little to do with the mortgage:
How did the debt get here?
Perhaps the debt resulted from a one-time circumstance—a renovation, unexpected home repair, separation, major family expense or temporary reduction in income.
Those situations can be very different from a household that is consistently spending more each month than it earns.
If there is an ongoing cash-flow shortfall, refinancing today's credit-card and line-of-credit balances may provide temporary relief without addressing the underlying problem.
Over time, those accounts can begin accumulating balances again. The homeowner could then have the original debt incorporated into the mortgage plus new consumer debt.
A refinance can restructure debt. A successful refinance also needs a plan for what happens afterwards.
Home Equity Can Create Options—but How Much Is Accessible?
Homeowners sometimes look at the estimated value of their property, subtract their mortgage balance and assume the difference is available to borrow.
It isn't necessarily that simple.
The amount of equity that may be accessible can depend on several factors, including:
- the property's current value and existing mortgage balance;
- income and employment stability;
- credit history;
- existing debts and overall affordability; and
- lender guidelines and maximum loan-to-value requirements.
Property values can also change.
Home equity can therefore be a valuable financial resource, but a financial plan should be based on today's numbers rather than assumptions about future property appreciation.
If a Mortgage Is Buying Time, What's the Plan?
There are circumstances where traditional financing may not currently be available and alternative or private lending can provide an important short-term solution.
The mortgage may create time to improve credit, reduce debt, stabilize income, resolve a tax obligation, sell a property or eventually return to traditional financing.
But buying time is only valuable if something is expected to change during that time.
Before entering a short-term mortgage, an important question is:
What will be different when this mortgage comes due?
Think of the mortgage as a bridge. The exit strategy is how you get to the other side.
Knowing the destination should be part of the plan before crossing the bridge.
Does Your Refinance Pass the Test?
Before using home equity to consolidate debt, I believe there are six useful questions to consider:
1. What caused the debt? Understanding whether the debt resulted from a one-time event or an ongoing cash-flow issue can influence the appropriate strategy.
2. What will change after the refinance? A new mortgage should be accompanied by a plan for what happens next.
3. Will monthly cash flow genuinely improve? Consider the complete household budget, not simply the mortgage payment.
4. What is the total cost? A lower interest rate or payment needs to be considered alongside the repayment period and overall borrowing cost.
5. How will you prevent the debt from returning? If revolving credit remains available after consolidation, there should be a strategy for its future use.
6. Will you be financially stronger a year or two from now? This brings the other questions together. The purpose of the refinance should be to improve the longer-term financial picture.
Can You Refinance—or Should You Refinance?
These are two different questions.
For some homeowners, refinancing can be an effective strategy to consolidate higher-interest debt, improve cash flow and establish a more manageable repayment plan.
For others, another mortgage may simply postpone a larger financial issue.
There may also be situations where the appropriate next conversation involves other professionals, such as an accountant, financial planner, lawyer, Licensed Insolvency Trustee or Realtor.
The purpose of mortgage advice shouldn't be to arrange another mortgage at all costs.
It should be to understand the homeowner's situation, explore the available options and help them make an informed decision while meaningful options are still available.
The Bottom Line
A refinance should do more than create a lower payment. It should have a purpose and a plan.
Before using your home equity to consolidate debt, ask:
What created the debt? What changes afterwards? And will this decision leave me in a stronger financial position?
Those questions can help shift the conversation from simply obtaining another mortgage to building a longer-term financial strategy.
Learn. Prepare. Plan.
Every homeowner's financial situation is different. Mortgage qualification, available equity, rates, costs and lending options depend on individual circumstances. This information is intended for general educational purposes and should not be considered financial, legal or insolvency advice.
Mortgage Renewals: More Than a Rate Decision
Why Your Mortgage Renewal Deserves a Strategic Review
February 25, 2026
For many homeowners, a mortgage renewal notice arrives 90 to 120 days before their mortgage term matures.
The process often appears simple. Your lender provides a renewal offer with a new rate and term, and all that is required is a signature.
But a mortgage renewal is much more than paperwork. It is an opportunity to review where you have been financially, where you are today, and where you want to go next.
As we move through 2026, more than one million Canadian mortgages are expected to come up for renewal. For many homeowners, this may be the first renewal since interest rates began rising several years ago.
Property Journey Insight: Rather than viewing renewal as a transaction, it can be valuable to view it as a financial checkpoint.
Has Your Life Changed Since Your Last Mortgage Term?
Five years ago, your financial situation may have looked very different. Since then:
- Your income may have increased.
- Your family situation may have changed.
- Children may be approaching university.
- Renovation plans may have emerged.
- Consumer debt may have accumulated.
- Your home's value may have increased significantly.
Yet many homeowners simply accept the renewal offer provided by their lender without reviewing whether their current mortgage structure still supports their goals.
A renewal should not only focus on the rate being offered. It should also consider whether the mortgage continues to fit your evolving financial situation.
Understanding the Equity You Have Built
One of the most important changes over the course of a mortgage term is the equity that homeowners build.
Each mortgage payment reduces a portion of the principal balance. Over time, this can create significant equity within the property. For example:
Home Value | $1,000,000 |
Current Mortgage Balance | $600,000 |
Maximum Refinancing Amount (80% Loan-to-Value) | $800,000 |
Potential Equity Access | Up to $200,000 |
This does not mean a homeowner should automatically borrow additional funds. However, understanding available equity creates options.
How Equity Can Support Financial Goals
When used strategically, home equity can become an important financial planning tool. Potential uses may include:
Debt Consolidation
Many Canadians carry higher-interest debt through credit cards, lines of credit, or personal loans. Consolidating those obligations into mortgage financing can often reduce monthly debt servicing costs and improve cash flow.
Education Funding
Parents may choose to use available equity to help fund post-secondary education expenses for their children.
Home Improvements
Renovations can improve both enjoyment of a home and long-term property value.
Emergency Planning
Available equity can provide flexibility when unexpected life events or expenses arise.
Property Journey Insight: The key is understanding your options before decisions need to be made.
Stability Versus Flexibility
One of the most important renewal decisions is determining whether your next mortgage term should prioritize stability, flexibility, or a balance of both.
Stability Protects
For some homeowners, stability may be the priority. This could include:
- Predictable payments
- Long-term certainty
- Reduced exposure to future changes
- Greater peace of mind
Flexibility Creates Options
For others, flexibility may be more important. This could include:
- Future refinancing opportunities
- Access to home equity
- Debt consolidation strategies
- Planning for future investments or expenses
There is no universal answer. The right structure depends on your financial objectives, risk tolerance, and future plans.
Accepting Versus Consulting
There is nothing wrong with accepting a lender's renewal offer. However, there can be significant value in reviewing that offer before signing.
A mortgage review may uncover:
- Better mortgage structuring opportunities
- Improved flexibility
- Cash flow enhancements
- Equity planning opportunities
- Long-term financial efficiencies
You do not necessarily need to change lenders. The goal is simply to ensure your next mortgage term aligns with your current needs and future goals.
Your Property Journey Continues
A mortgage renewal is not the end of a mortgage term. It is the beginning of the next chapter in your property journey.
Where you started, where you are today, and where you are heading next all matter. Your financial goals evolve. Your property journey evolves. Your mortgage should evolve with it.
Before signing your next renewal, take the time to ensure it has been structured intentionally for stability, flexibility, or the right balance of both.
Property Journey Insight: The best mortgage renewal is not simply accepted. It is thoughtfully designed.
I'm here to help you understand your options, answer your questions, and guide you through every step of the mortgage process. Because every property journey is unique. Every mortgage tells a story. My role is to help you understand your options so you can make informed decisions with confidence.
Ready to start your Property Journey? Connect with me today to get started.
Derrick Kapitan Mortgage Agent Level 1 | Lic. M24003293 The Mortgage Coach | FSRA #13120
Sharing Knowledge. Sharing Life Experience. Continuous Learning.
📞 647-219-4743 📧 derrickkapitan@themortgagecoach.ca 🌐 www.themortgagecoach.ca
Week 34 - Aug 23 2026
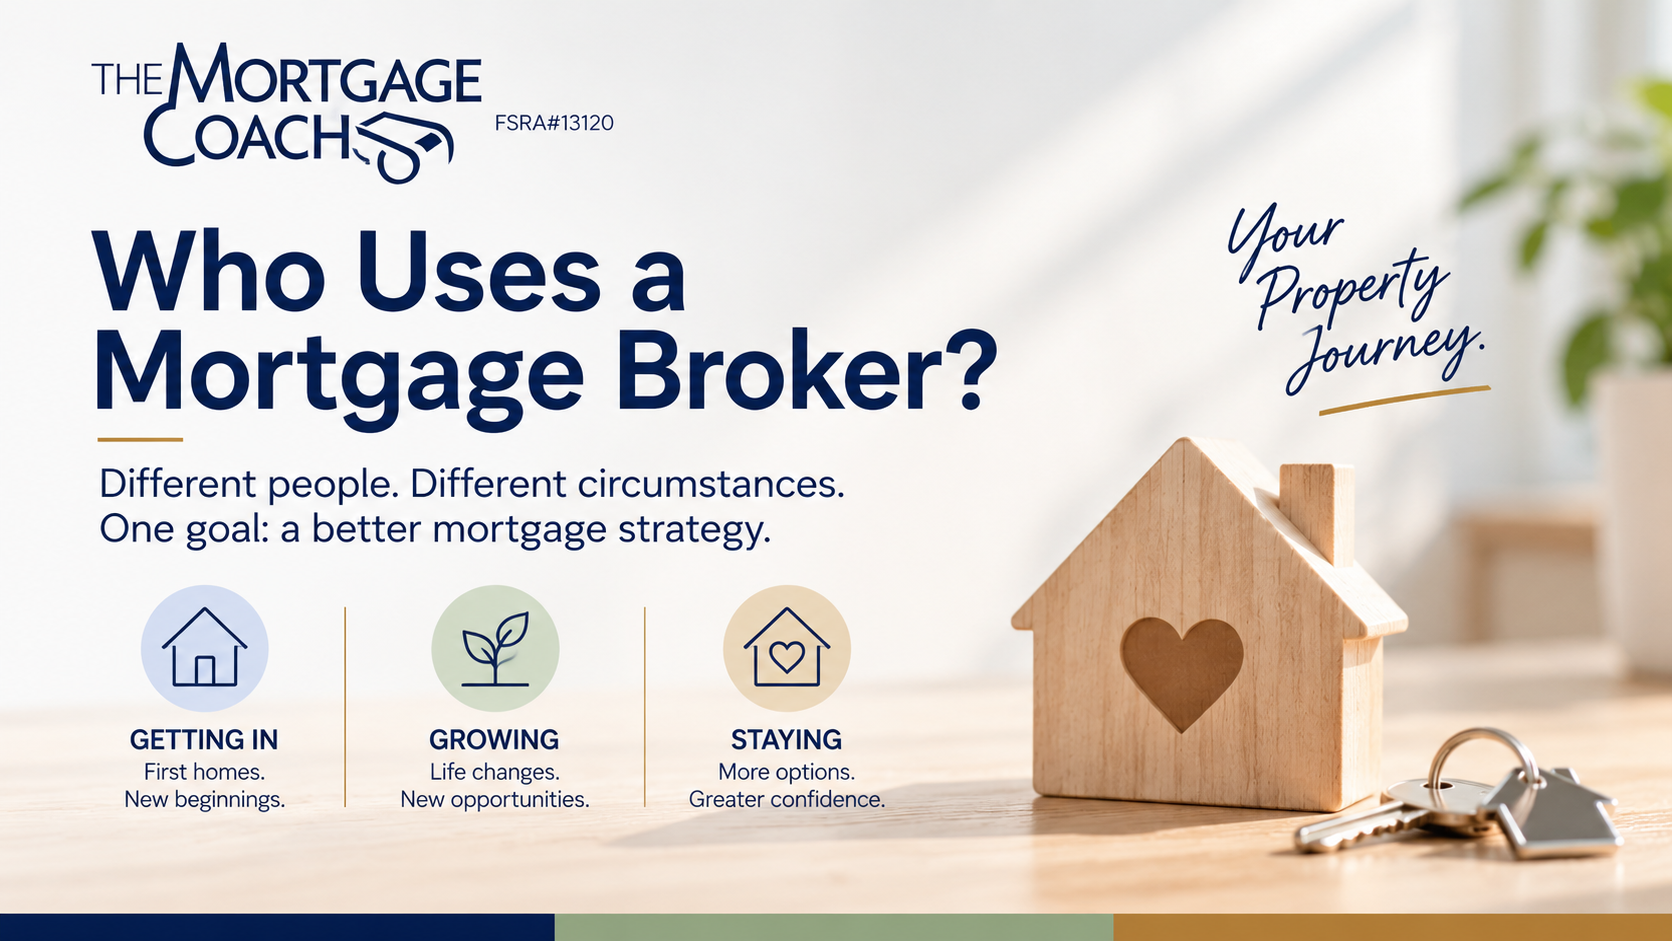
Who Uses a Mortgage Broker? Your Property Journey
September 08, 2026
Who uses a mortgage broker? Explore how mortgage advice can help first-time buyers, homeowners, self-employed borrowers and those planning for retirement.
Who Uses a Mortgage Broker?
Different People. Different Circumstances. Different Conversations.
When you hear the words mortgage broker, who comes to mind?
A first-time homebuyer?
Someone who has been declined by their bank?
Those can certainly be mortgage broker clients, but they represent only part of the picture.
People seek mortgage advice at many different stages of homeownership and for many different reasons. Their income changes. Families grow. Careers evolve. Credit can be challenged. Equity accumulates. Retirement approaches.
When I think about my own Property Journey, I've needed mortgages at very different stages of my life. I wasn't the same person, with the same circumstances or priorities, at each stage.
That's an important reminder: behind every mortgage is a person going through something.
It might be excitement, uncertainty, change or simply the need to understand what comes next.
That's why I think about homeownership through three broad stages of the Property Journey: Getting In, Growing and Staying.
Getting In: The First-Time Homebuyer
I still remember buying my first home.
What do I remember most?
It wasn't the mortgage. It was getting the keys.
That's easy to forget when we work around mortgages every day. First-time buyers aren't dreaming about amortization periods, qualifying ratios or mortgage terms. They're imagining where they're going to live and what owning their first home might feel like.
Alongside that excitement, however, often comes uncertainty.
Can I afford this?
How much do I need for a down payment?
What about closing costs?
Should I choose a fixed or variable mortgage?
Before falling in love with a property, it can be helpful to understand the financial side of the purchase.
Learn. Prepare. Plan.
The objective isn't simply to obtain a mortgage. It's to take that first step into homeownership with a clearer understanding of what you can comfortably afford.
That's Getting In.
Growing: When Your Life Changes
If you've already had a mortgage, it can be tempting to assume the next decision will be straightforward.
But think about how much can change during a typical mortgage term.
Your income may be different. Your family may have grown. Your debts may have changed. Your property may have increased or decreased in value. Your financial priorities may be completely different.
I've owned property at different stages of my own life, and the person buying my first home wasn't the same person making later property decisions.
That's why a mortgage renewal shouldn't necessarily be viewed as simply another piece of paperwork.
It can be an opportunity to ask:
Does my mortgage still fit my life today?
Review the mortgage. Compare the available options. Reassess what you're trying to accomplish.
Review. Compare. Reassess.
Sometimes Growing isn't about buying another property. It's about making a more informed decision with the property and mortgage you already have.
Business for Self: Telling the Story Behind the Numbers
For Canadians who are self-employed, the mortgage conversation can look different.
Someone can operate a successful business and still wonder why obtaining a mortgage seems more complicated than expected.
That's because self-employed income isn't always represented by a regular paycheque.
A lender may need to consider documents such as tax returns, Notices of Assessment, financial statements and business bank statements. Depending on the circumstances, additional documentation may also be required.
The objective is not simply to collect paperwork.
It's to help establish a clear and supportable picture of the borrower's income and financial circumstances.
Different lenders may also have different approaches to assessing business-for-self borrowers.
Document. Explain. Support.
Sometimes the numbers don't tell the whole story. Preparation can help make that story easier to understand.
When Credit Has Been Challenged
Credit can be one of the more uncomfortable parts of a mortgage conversation.
A missed payment, high balances or an unexpected financial event can appear on a credit report long after the circumstances surrounding it have passed.
For someone worried about their credit, the biggest concern may not even be:
Can I get a mortgage?
It might be:
What is someone going to think when they see my credit report?
A more useful starting point is understanding what happened.
What is currently affecting the credit profile? What can be improved? How much time could improvement take?
Sometimes there may be an appropriate mortgage solution today. Other times, the better strategy may be preparing for tomorrow.
Understand. Rebuild. Prepare.
A credit report tells part of the financial history. The next conversation is about what happens from here.
Growing: Using Home Equity With Purpose
Over time, homeowners may build equity in their property.
That equity can create possibilities.
Perhaps you're considering a renovation, helping a family member, purchasing another property or consolidating higher-interest debt.
A common question might be:
“How much equity can I access?”
But I believe another question should come first:
“What are we trying to accomplish?”
Being able to borrow doesn't automatically mean borrowing is the right decision.
Any strategy involving home equity should consider three things:
Purpose. Cost. Outcome.
What is the money being used for?
What will accessing it cost?
And perhaps most importantly, does the strategy leave you in a better financial position?
Equity creates options. Strategy helps determine which options make sense.
That's another part of Growing.
Staying: When Home Means More Than Market Value
Eventually, the mortgage conversation can change again.
For someone who has owned a home for decades, that property may represent considerably more than its market value.
It's family dinners.
Birthdays and holidays.
Neighbours who became friends.
The garden you've cared for.
The kitchen table where countless conversations happened.
So when retirement approaches and cash flow becomes tighter, saying “Why don't you just sell?” may overlook an important part of the conversation.
For some homeowners, the question isn't where they want to move next.
It's:
“How can I comfortably stay?”
That conversation might include retirement cash flow, an existing mortgage, other debts, accumulated home equity and family considerations.
For some homeowners, it may also mean learning about options such as a reverse mortgage.
Not every solution is appropriate for every homeowner. Understanding the advantages, costs, implications and alternatives should come before making a decision.
Understand. Consider. Decide.
Sometimes the next stage of the Property Journey isn't going anywhere.
It's Staying.
So, Who Uses a Mortgage Broker?
There really isn't one answer.
It could be someone buying their first home.
Someone renewing a mortgage they've had for years.
A business owner whose income requires a little more explanation.
Someone rebuilding their credit.
A homeowner considering whether to use accumulated equity.
Or someone approaching retirement who wants to understand the options for remaining in the home they love.
The mortgage may be the financial tool, but the person and their objectives should be the starting point.
Different people.
Different circumstances.
Different conversations.
Whether you're Getting In, Growing or Staying, sometimes the most valuable mortgage conversation happens long before you actually need the mortgage.
Education first. Strategy second. Pressure never.
Derrick KapitanMortgage Agent Level 1 | Lic. #M24003293The Mortgage Coach | FSRA #13120647.219.4743derrickkapitan@themortgagecoach.ca
Week 33 August 16 2026
Behind Every Mortgage Approval: Understanding the Mortgage Underwriting Process
September 08, 2026
Learn how the mortgage underwriting process works in Canada, what documents lenders review, and how preparation can help create a smoother mortgage journey.
Behind Every Mortgage Approval
Understanding the Mortgage Underwriting Process
When most people think about applying for a mortgage, they usually focus on three things:
- What interest rate will I get?
- What will my monthly payment be?
- How quickly can I be approved?
But there's another question that often goes unasked...
What actually happens after I submit my mortgage application?
That's where the mortgage underwriting process begins.
To many borrowers, it can feel like their application disappears into a "black box" while they wait for an answer. In reality, there's a structured review taking place behind the scenes.
As your Mortgage Agent, one of my roles is to prepare your application so it tells a complete, accurate financial story before it ever reaches the lender. The more complete your application is from the beginning, the smoother the journey tends to be.
Every Professional Needs the Right Tools
Think about the professionals you trust every day.
A mechanic needs diagnostic equipment.
An electrician needs testing tools.
A carpenter measures before making the first cut.
A chef relies on quality ingredients.
Without the right tools, even the most experienced professional can't do their best work.
Mortgage professionals are no different.
Our tools simply happen to be documents.
Throughout this week's Property Journey, I referred to these documents as The Mortgage Toolbox. Each tool serves a different purpose, but together they help tell your financial story and allow us to present your application as clearly as possible.
Let's take a look inside the toolbox.
Tool #1 – Understanding Your Income
Everything starts with your income.
Before recommending a lender or mortgage product, we first need to understand how you earn your income and whether it is stable, consistent, and sustainable.
Depending on your situation, we may request:
- Employment Letter
- Recent Pay Stubs
- T4 Slips
- Notice of Assessment
- Business Financial Statements (for self-employed borrowers)
These documents aren't collected simply to satisfy lender requirements.
They help us determine how much income can realistically be used to qualify and ensure the mortgage recommendation is suitable for your financial situation.
🏡 Property Journey Insight
Accurate information leads to better advice.
Tool #2 – Looking Beyond Your Credit Score
One of the biggest misconceptions about mortgages is that everything comes down to your credit score.
While your score is important, it only tells part of the story.
Underwriters also review:
- Payment history
- Existing debts
- Credit utilization
- Overall borrowing habits
Think about buying a used vehicle.
You wouldn't make your decision based only on how shiny the paint looks.
You'd also want to know what's happening under the hood.
Mortgage underwriting works much the same way.
🏡 Property Journey Insight
A mortgage decision is based on your overall financial picture—not just one number.
Tool #3 – Telling Your Financial Story
Every mortgage application tells a story.
Your income explains where you are today.
Your supporting documents explain how you got there.
Documents such as:
- Bank Statements
- Investment Statements
- Gift Letters
- Proof of Down Payment
help demonstrate your financial preparation.
When your financial story is complete before submission, there are fewer questions for the lender later.
That often means fewer delays and a smoother approval process.
🏡 Property Journey Insight
A complete financial story creates confidence.
Tool #4 – The Property Matters Too
A mortgage isn't approved based only on the borrower.
The property is also being evaluated.
Depending on the transaction, lenders may review:
- Agreement of Purchase and Sale
- Property Tax Information
- Condo Fees
- Home Insurance
- Property Appraisal
These documents help the lender understand the home that will secure the mortgage.
After all, a mortgage is about both the borrower and the property.
🏡 Property Journey Insight
Every successful mortgage balances both sides of the equation.
Tool #5 – Keeping the Process Moving
Imagine hiring a contractor who arrives without their tools.
The work can't begin until everything is available.
Mortgage applications are no different.
Some of the most common reasons for delays include:
- Expired Pay Stubs
- Missing Bank Statements
- Outdated Identification
- Unsigned Documents
- Older Mortgage Statements
If I ask you for an updated document—even one you've already provided—it's simply because lenders require current information before making a final decision.
🏡 Property Journey Insight
Preparation today helps prevent delays tomorrow.
Mortgage Approval Is a Team Effort
One of the things I enjoy most about being a Mortgage Agent is seeing how many professionals work together behind the scenes to help someone purchase, refinance, or renew their home.
While you may work directly with me, there is an entire team reviewing, verifying, and preparing your application before a lending decision is made.
That team may include:
- You, the Client
- Your Mortgage Agent
- Our Broker Underwriting Team
- The Lender's Underwriter
- The Property Appraiser
- Your Real Estate Lawyer
Everyone plays an important role.
When your documents are organized and up to date, our team can review your application thoroughly, identify potential concerns before they become problems, and present your financial story as clearly as possible to the lender.
Good preparation benefits everyone involved.
Final Thoughts
One of the questions I'm asked most often is:
"Why do you need so many documents?"
Hopefully, you now know the answer.
Mortgage documents aren't simply paperwork.
They're the tools we use to understand your financial story, recommend suitable mortgage solutions, and present your application as clearly and accurately as possible to the lender.
The more you understand the underwriting process, the more confident you'll feel throughout your own Property Journey.
At The Mortgage Coach, I believe education comes before decisions.
When you understand why something is needed—not just what is needed—you can move forward with greater confidence.
Continue Your Property Journey
Whether you're:
- Buying your first home
- Renewing your mortgage
- Refinancing your existing mortgage
- Self-employed
- Purchasing an investment property
I'm here to help you understand your options, answer your questions, and guide you through every step of the mortgage process.
Because every property journey is unique.
Every mortgage tells a story.
My role is to help you understand your options so you can make informed decisions with confidence.
Derrick KapitanMortgage Agent Level 1 | Lic. M24003293The Mortgage Coach | FSRA #13120
📞 647-219-4743 📧 derrickkapitan@themortgagecoach.ca 🌐 www.themortgagecoach.ca
Week 29 July 19 2026
Stay Connected
Subscribe to our Newsletter and you'll stay up to date on rates that help you save thousands in interest.